

Yet again, folk are missing the point.
What we’ve seen over the last few weeks has not been ‘risk off’. It’s not been ‘deleveraging’. And it almost certainly hasn’t been the ‘top’ in equities.
Instead - and, I know this isn’t a clickbaity line that will get clicks - it’s just been a good, old-fashioned sector rotation.
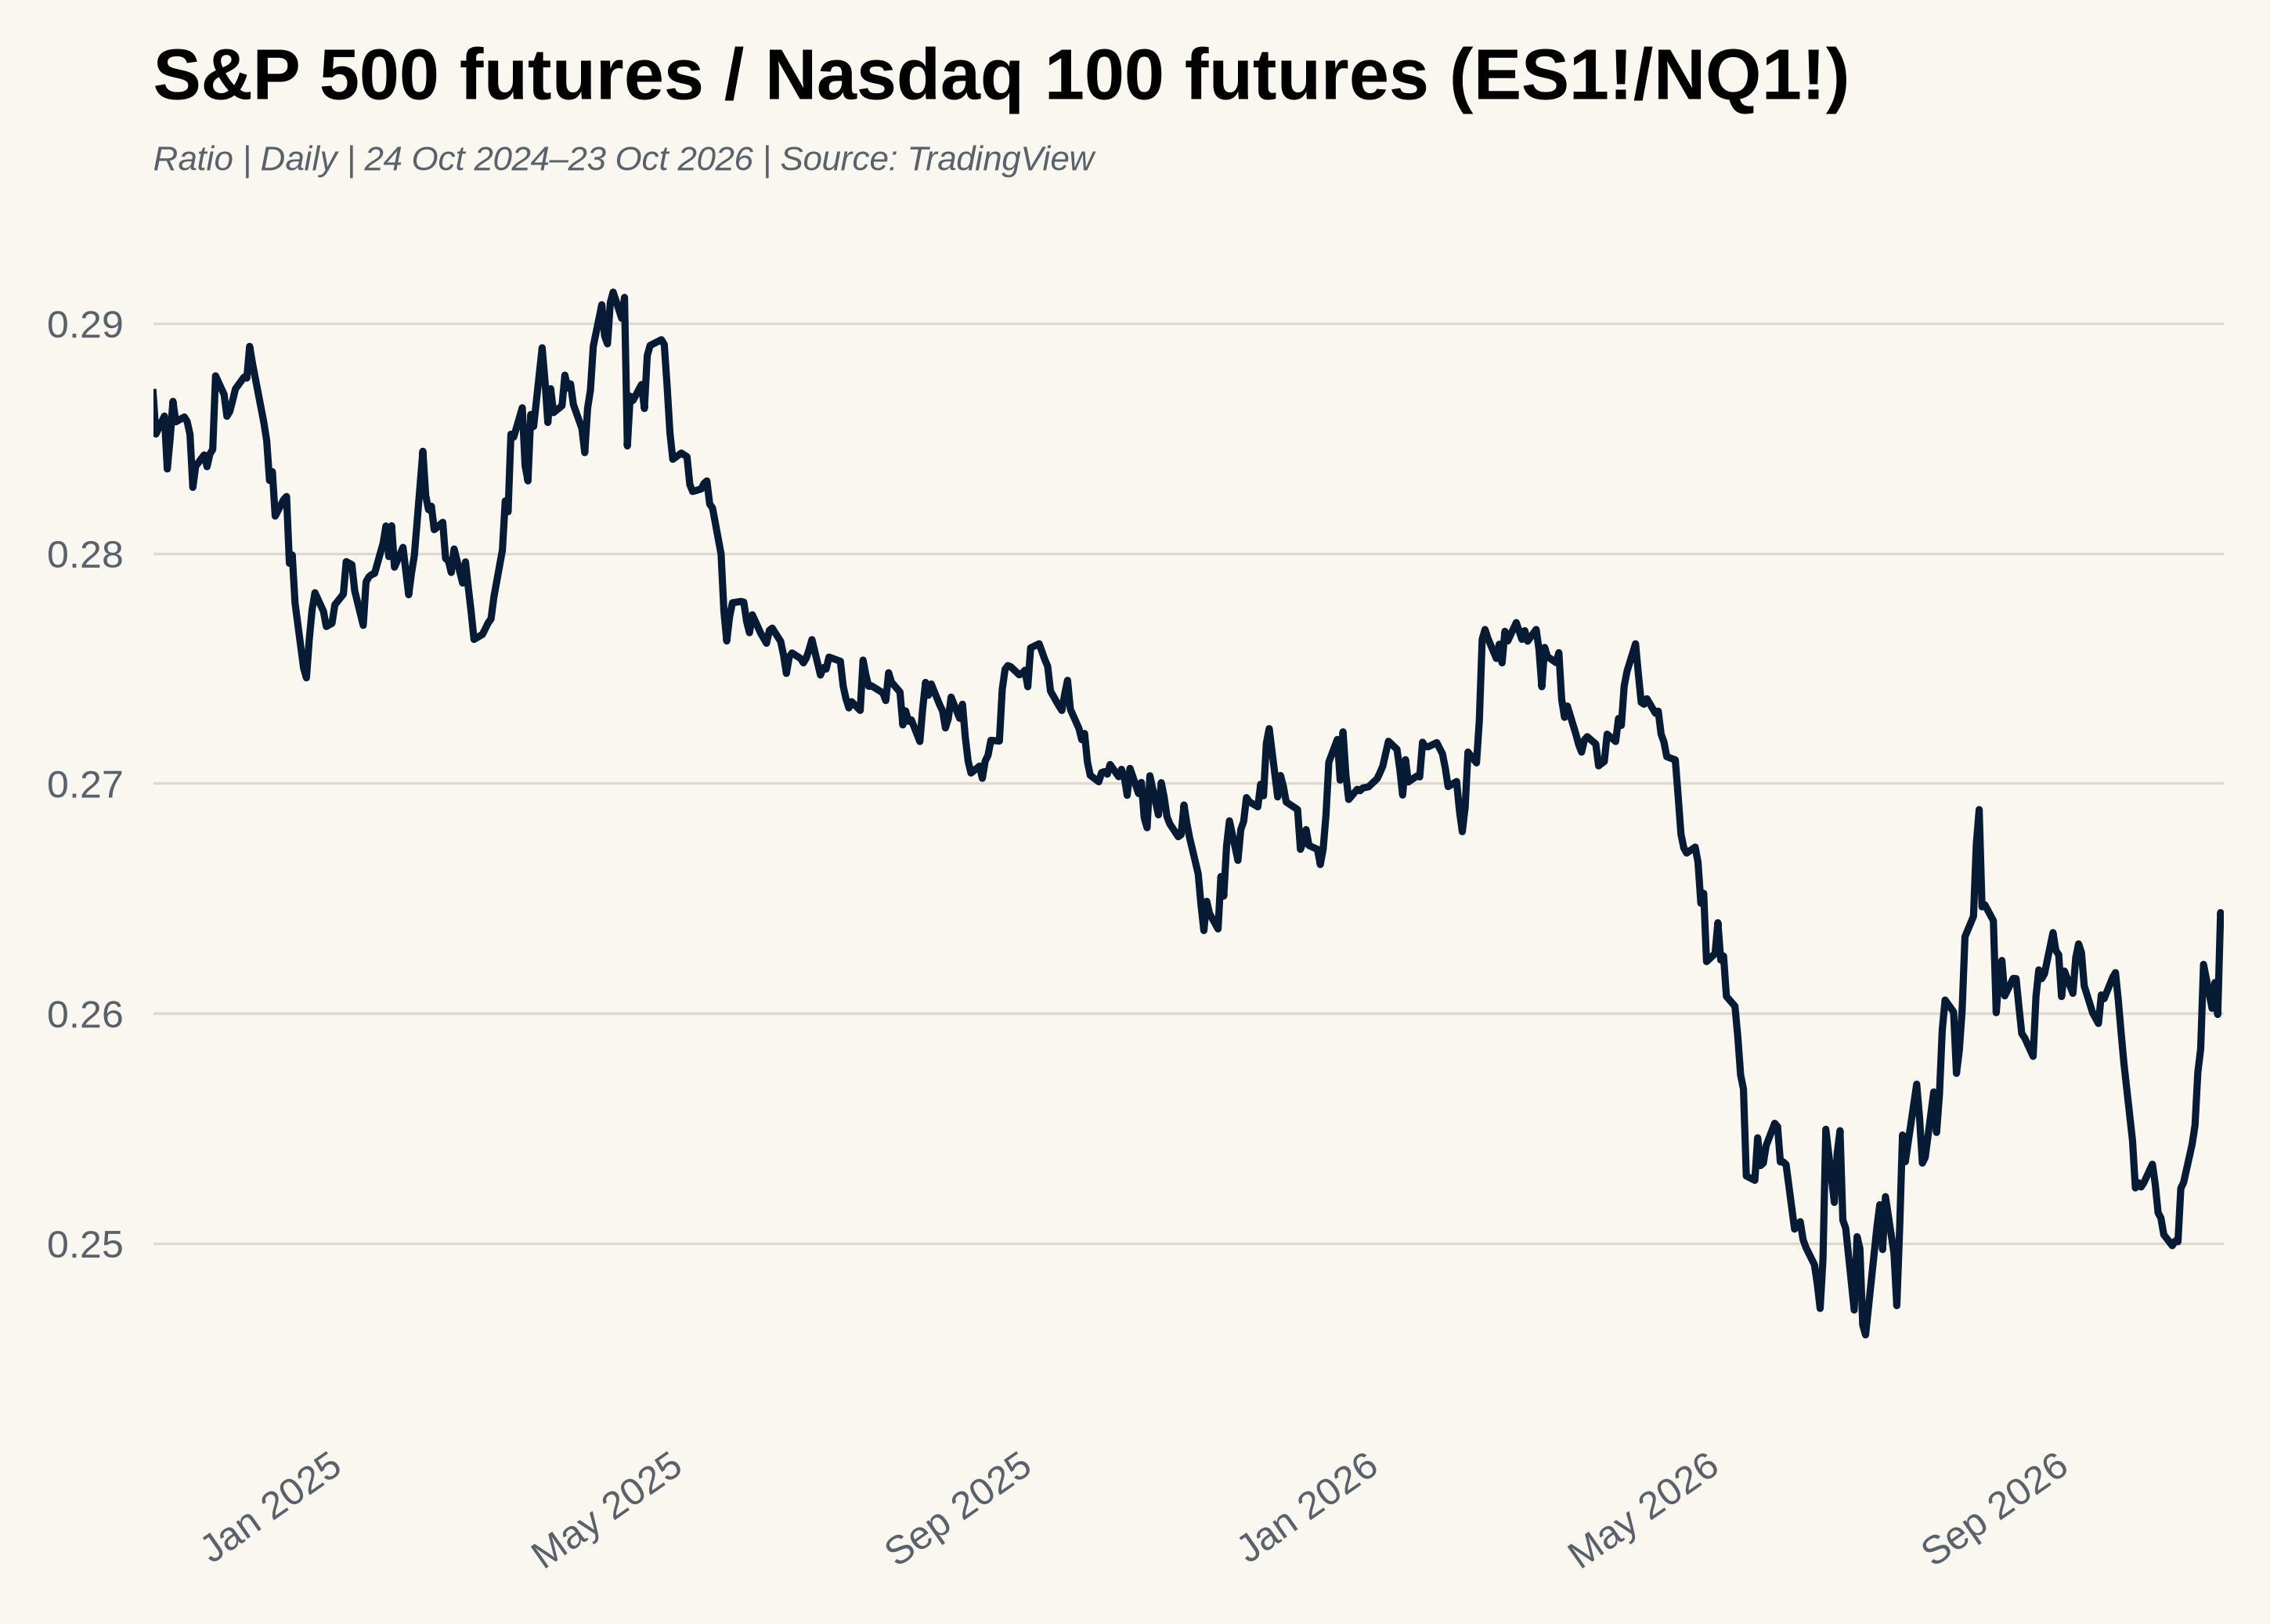
Look at the S&P compared to the Nasdaq, for instance.
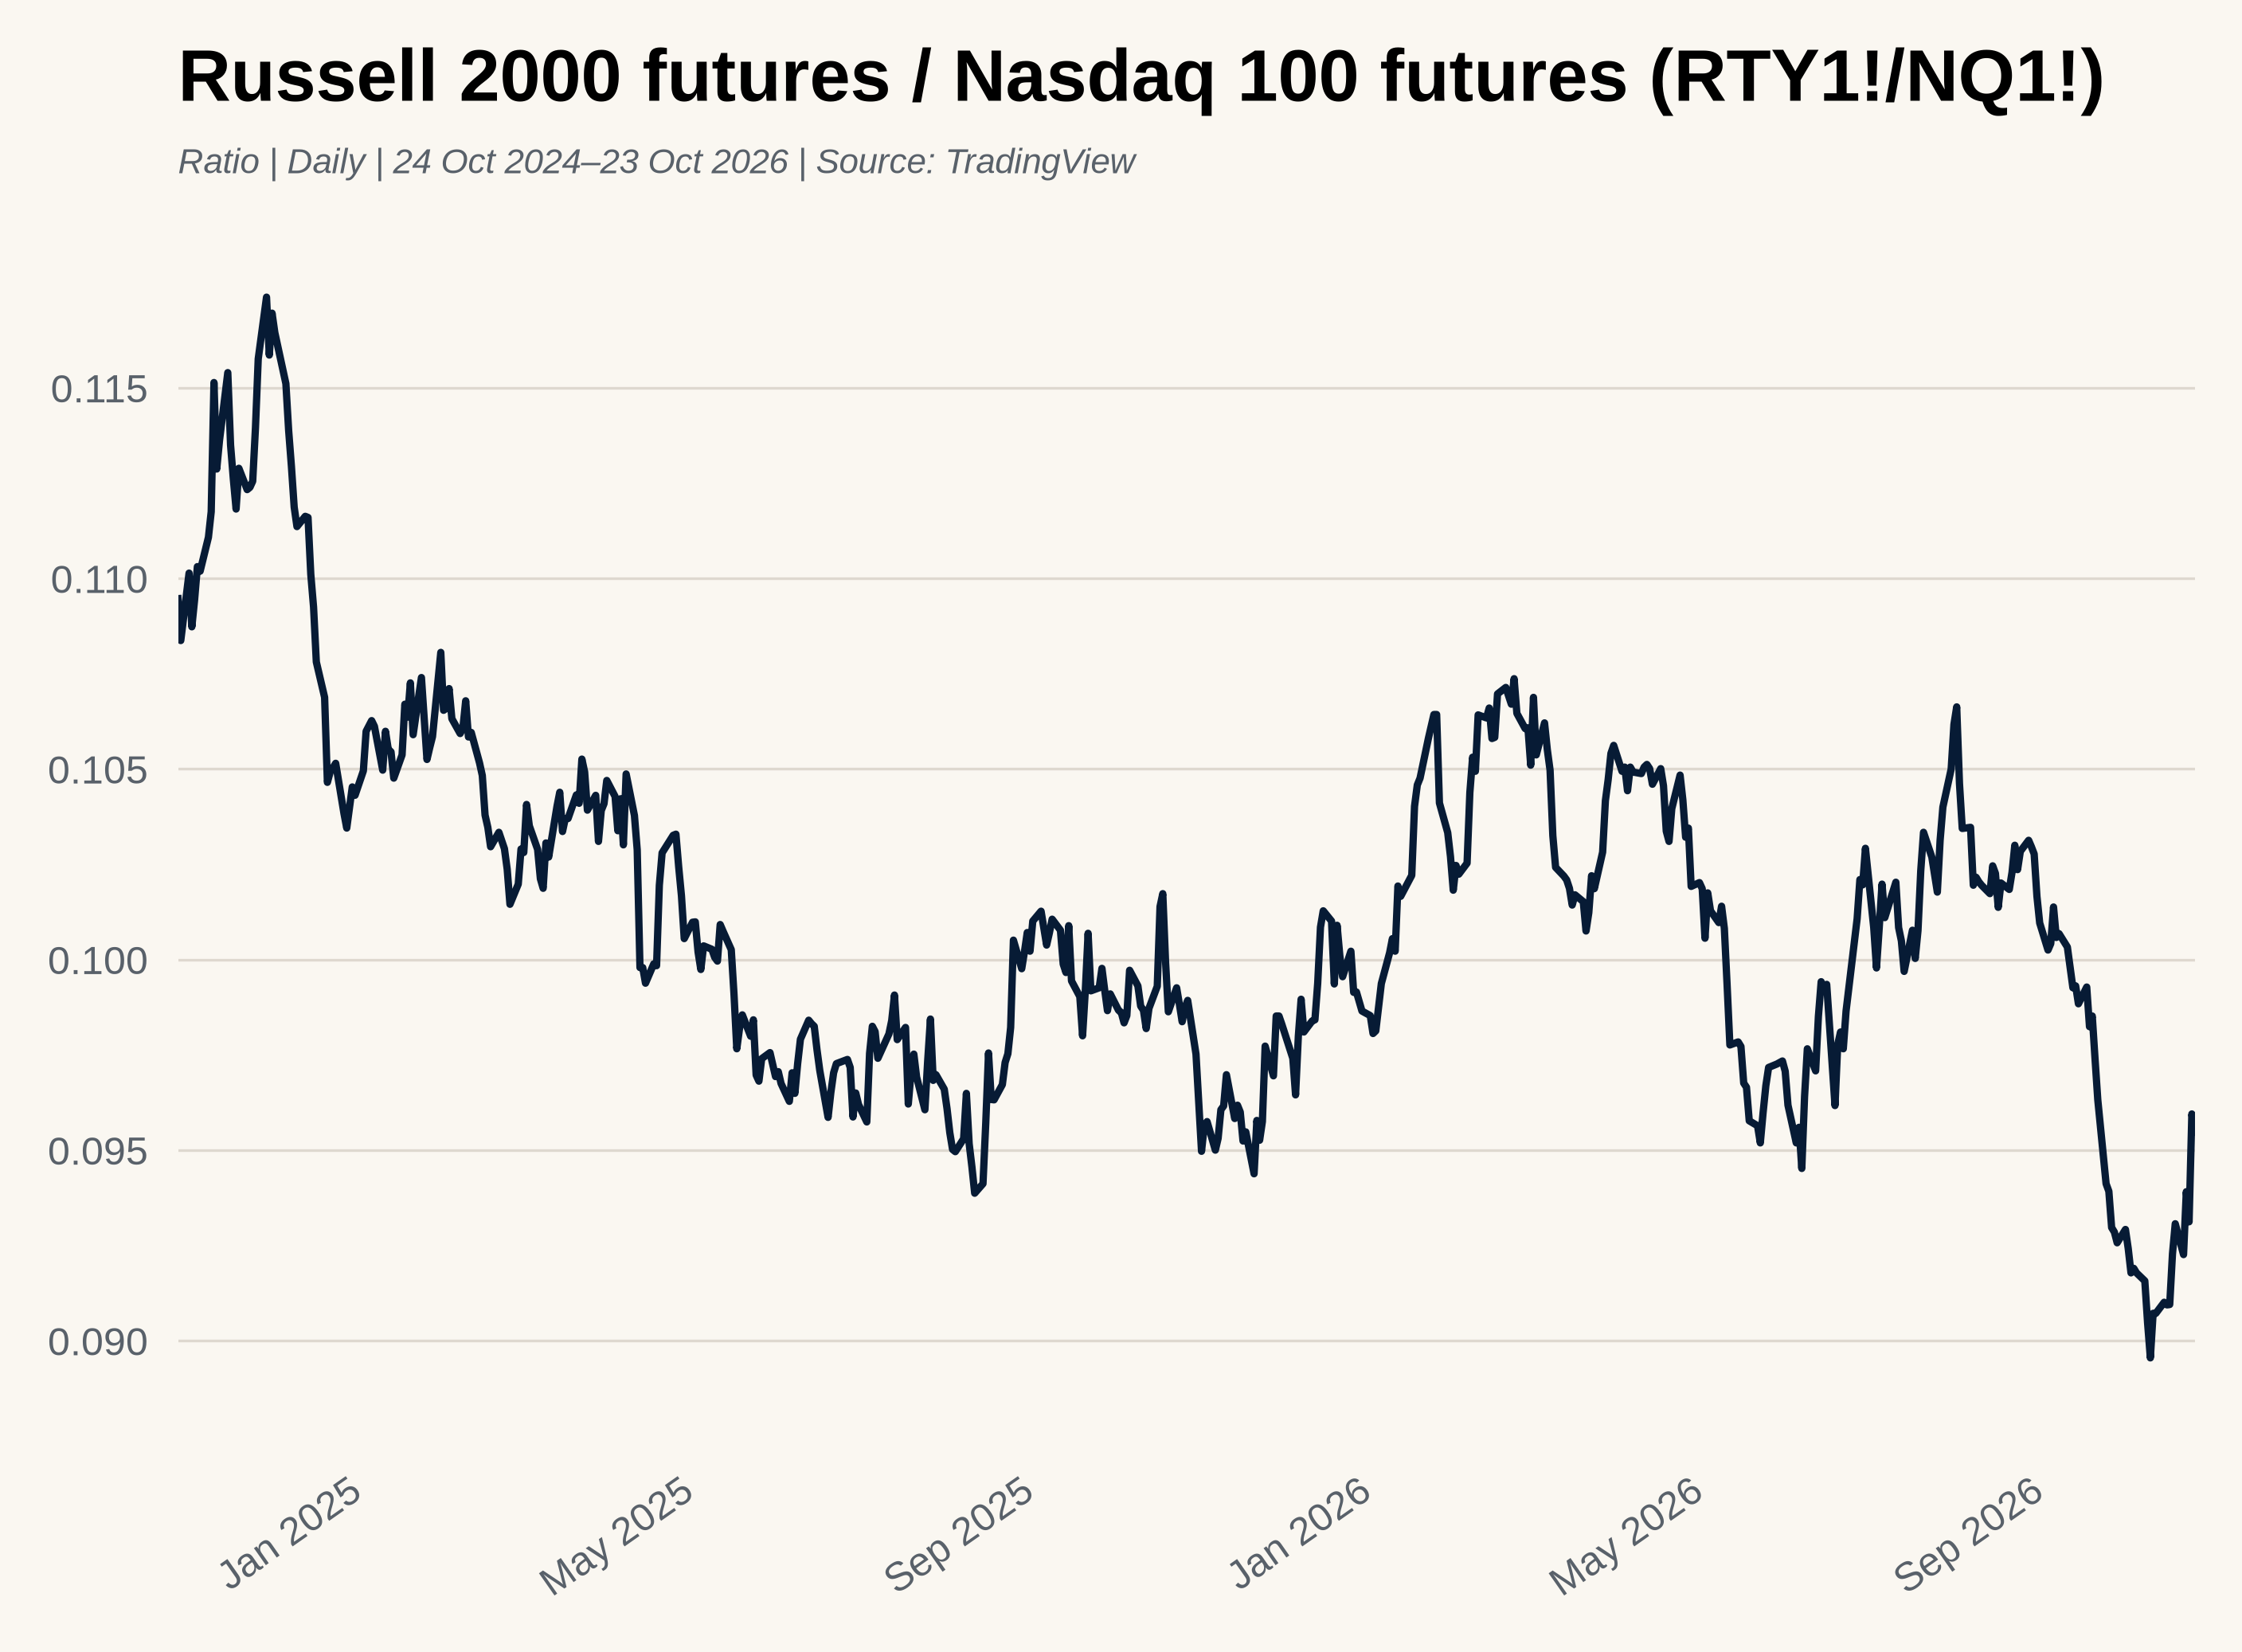
Or, the S&P compared to the small cap Russell 2000.
Or, even, just a view of the performance of each S&P sector this year.
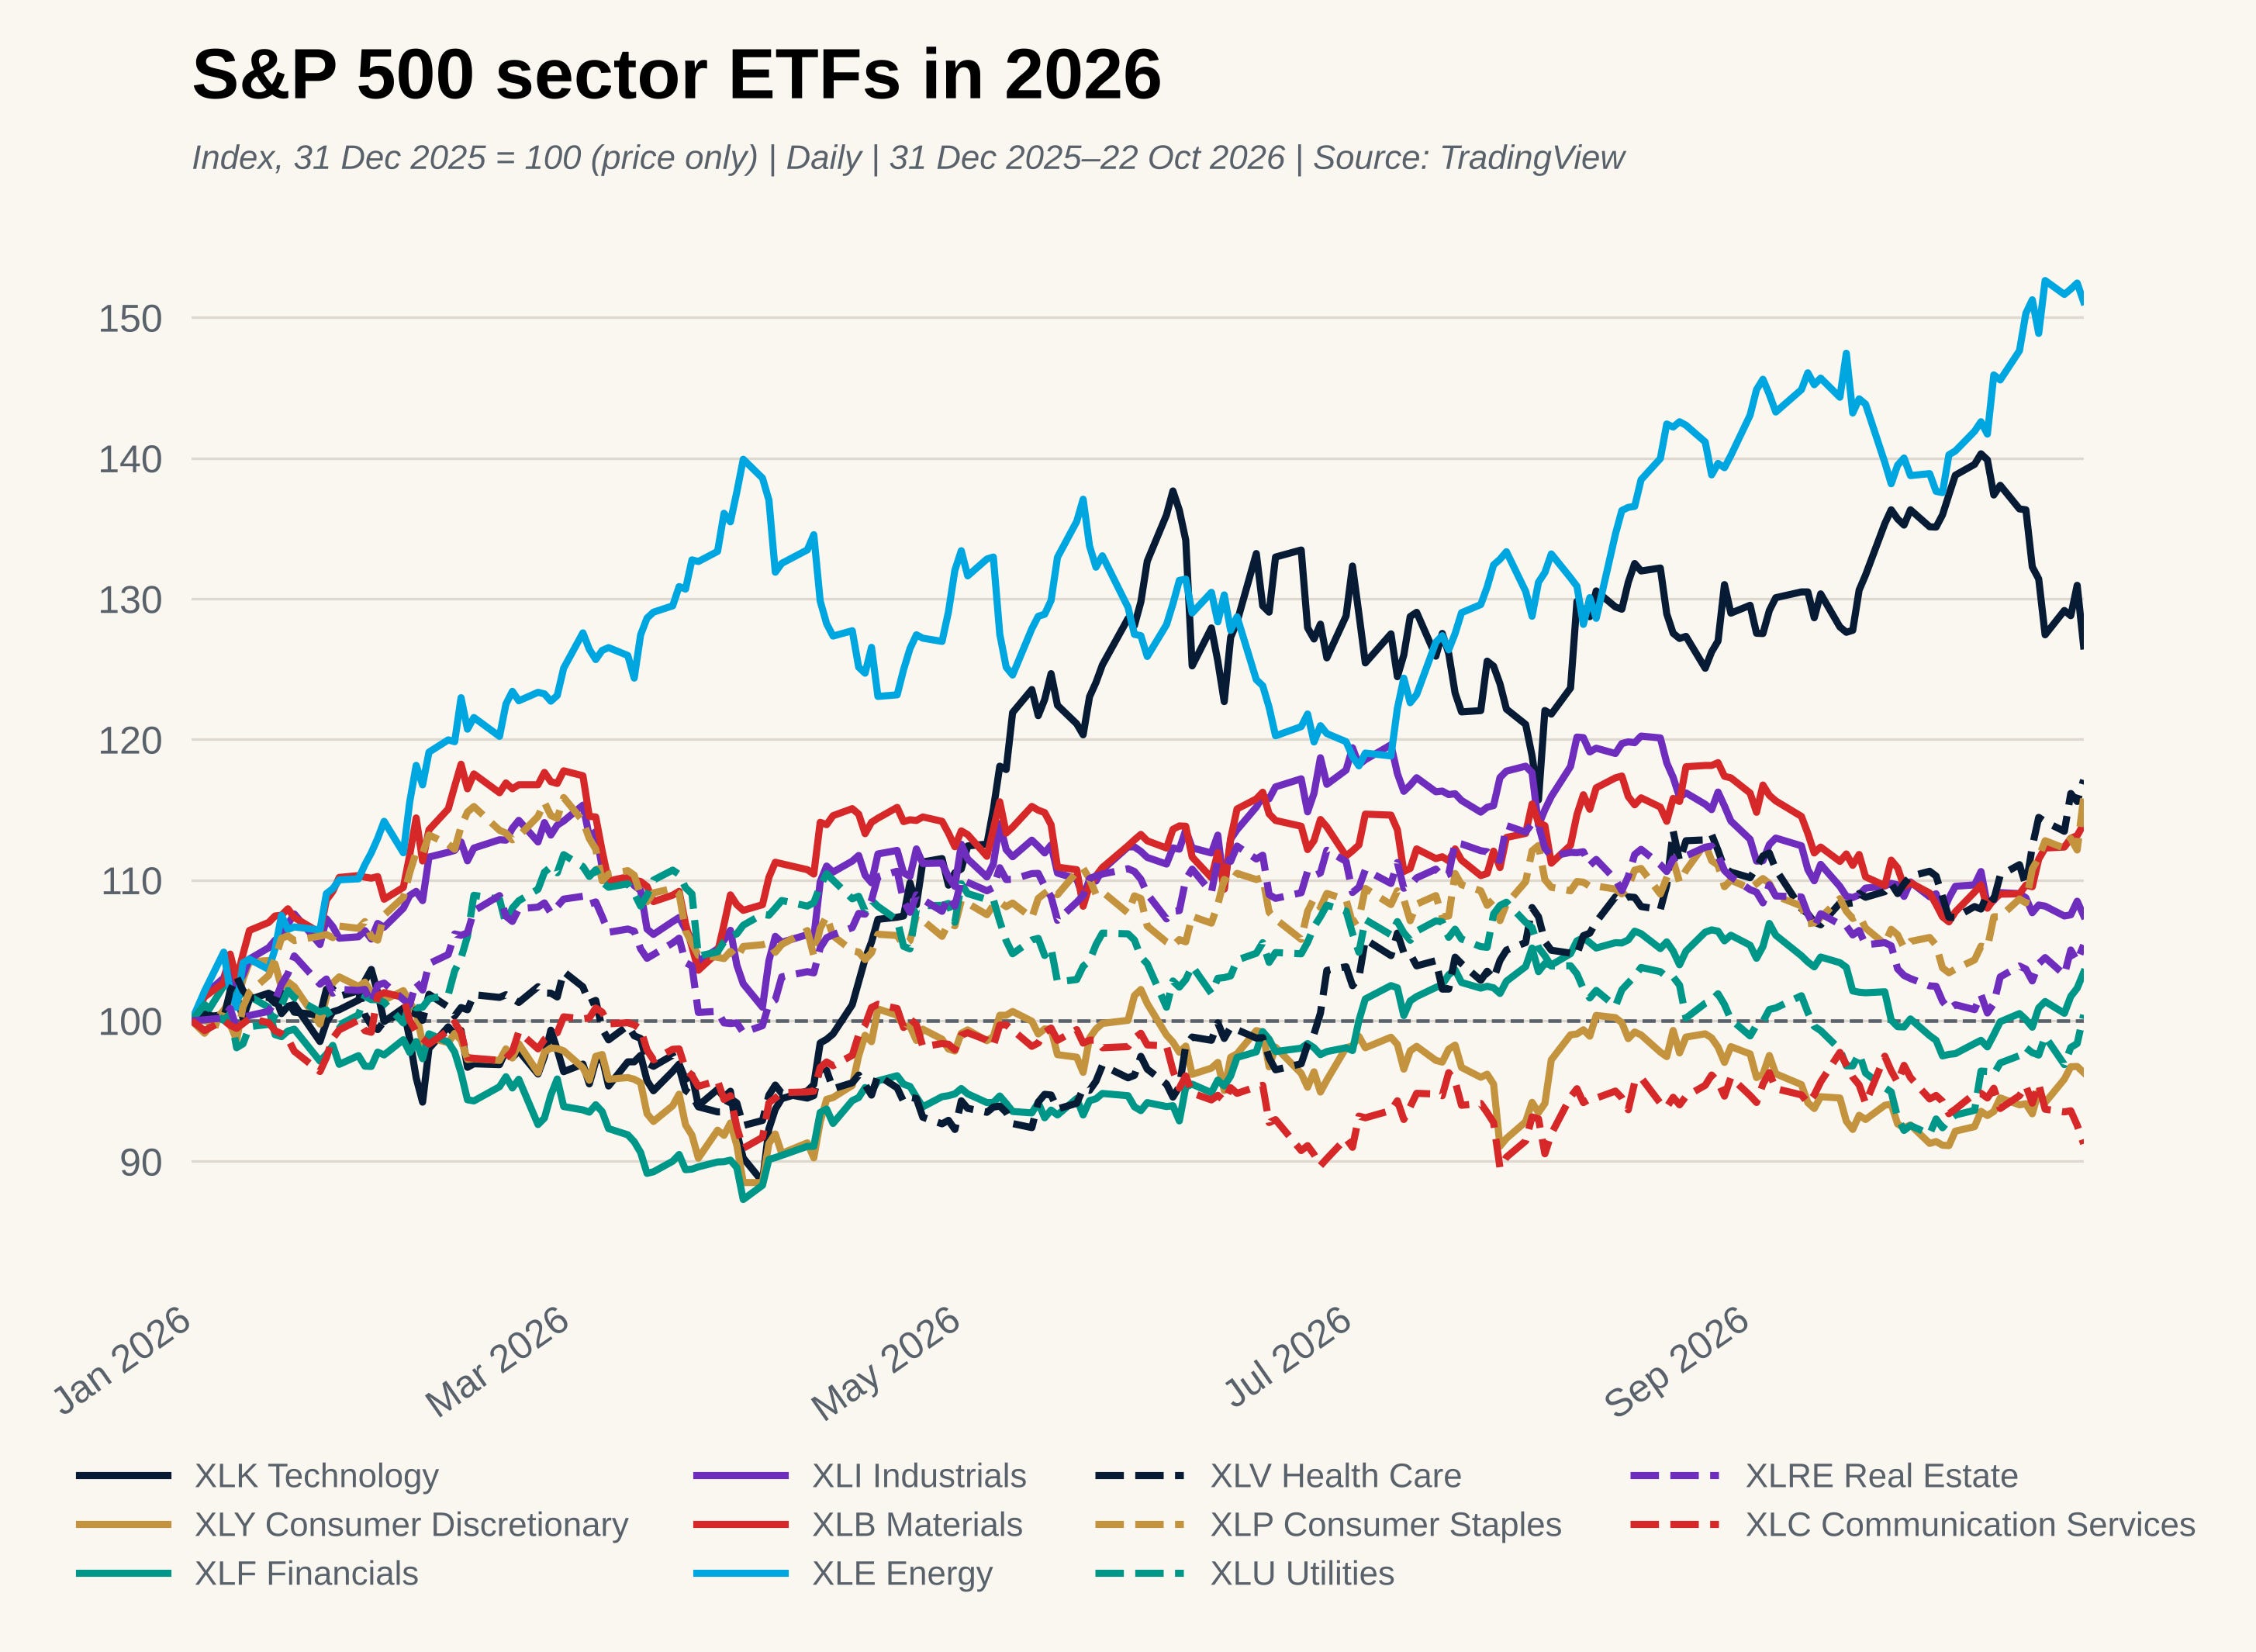
Quite obviously, what we see is an environment where participants are trimming their exposure to the megacap tech names, and instead allocating increasingly to other areas of the market.
This is no bad thing!!
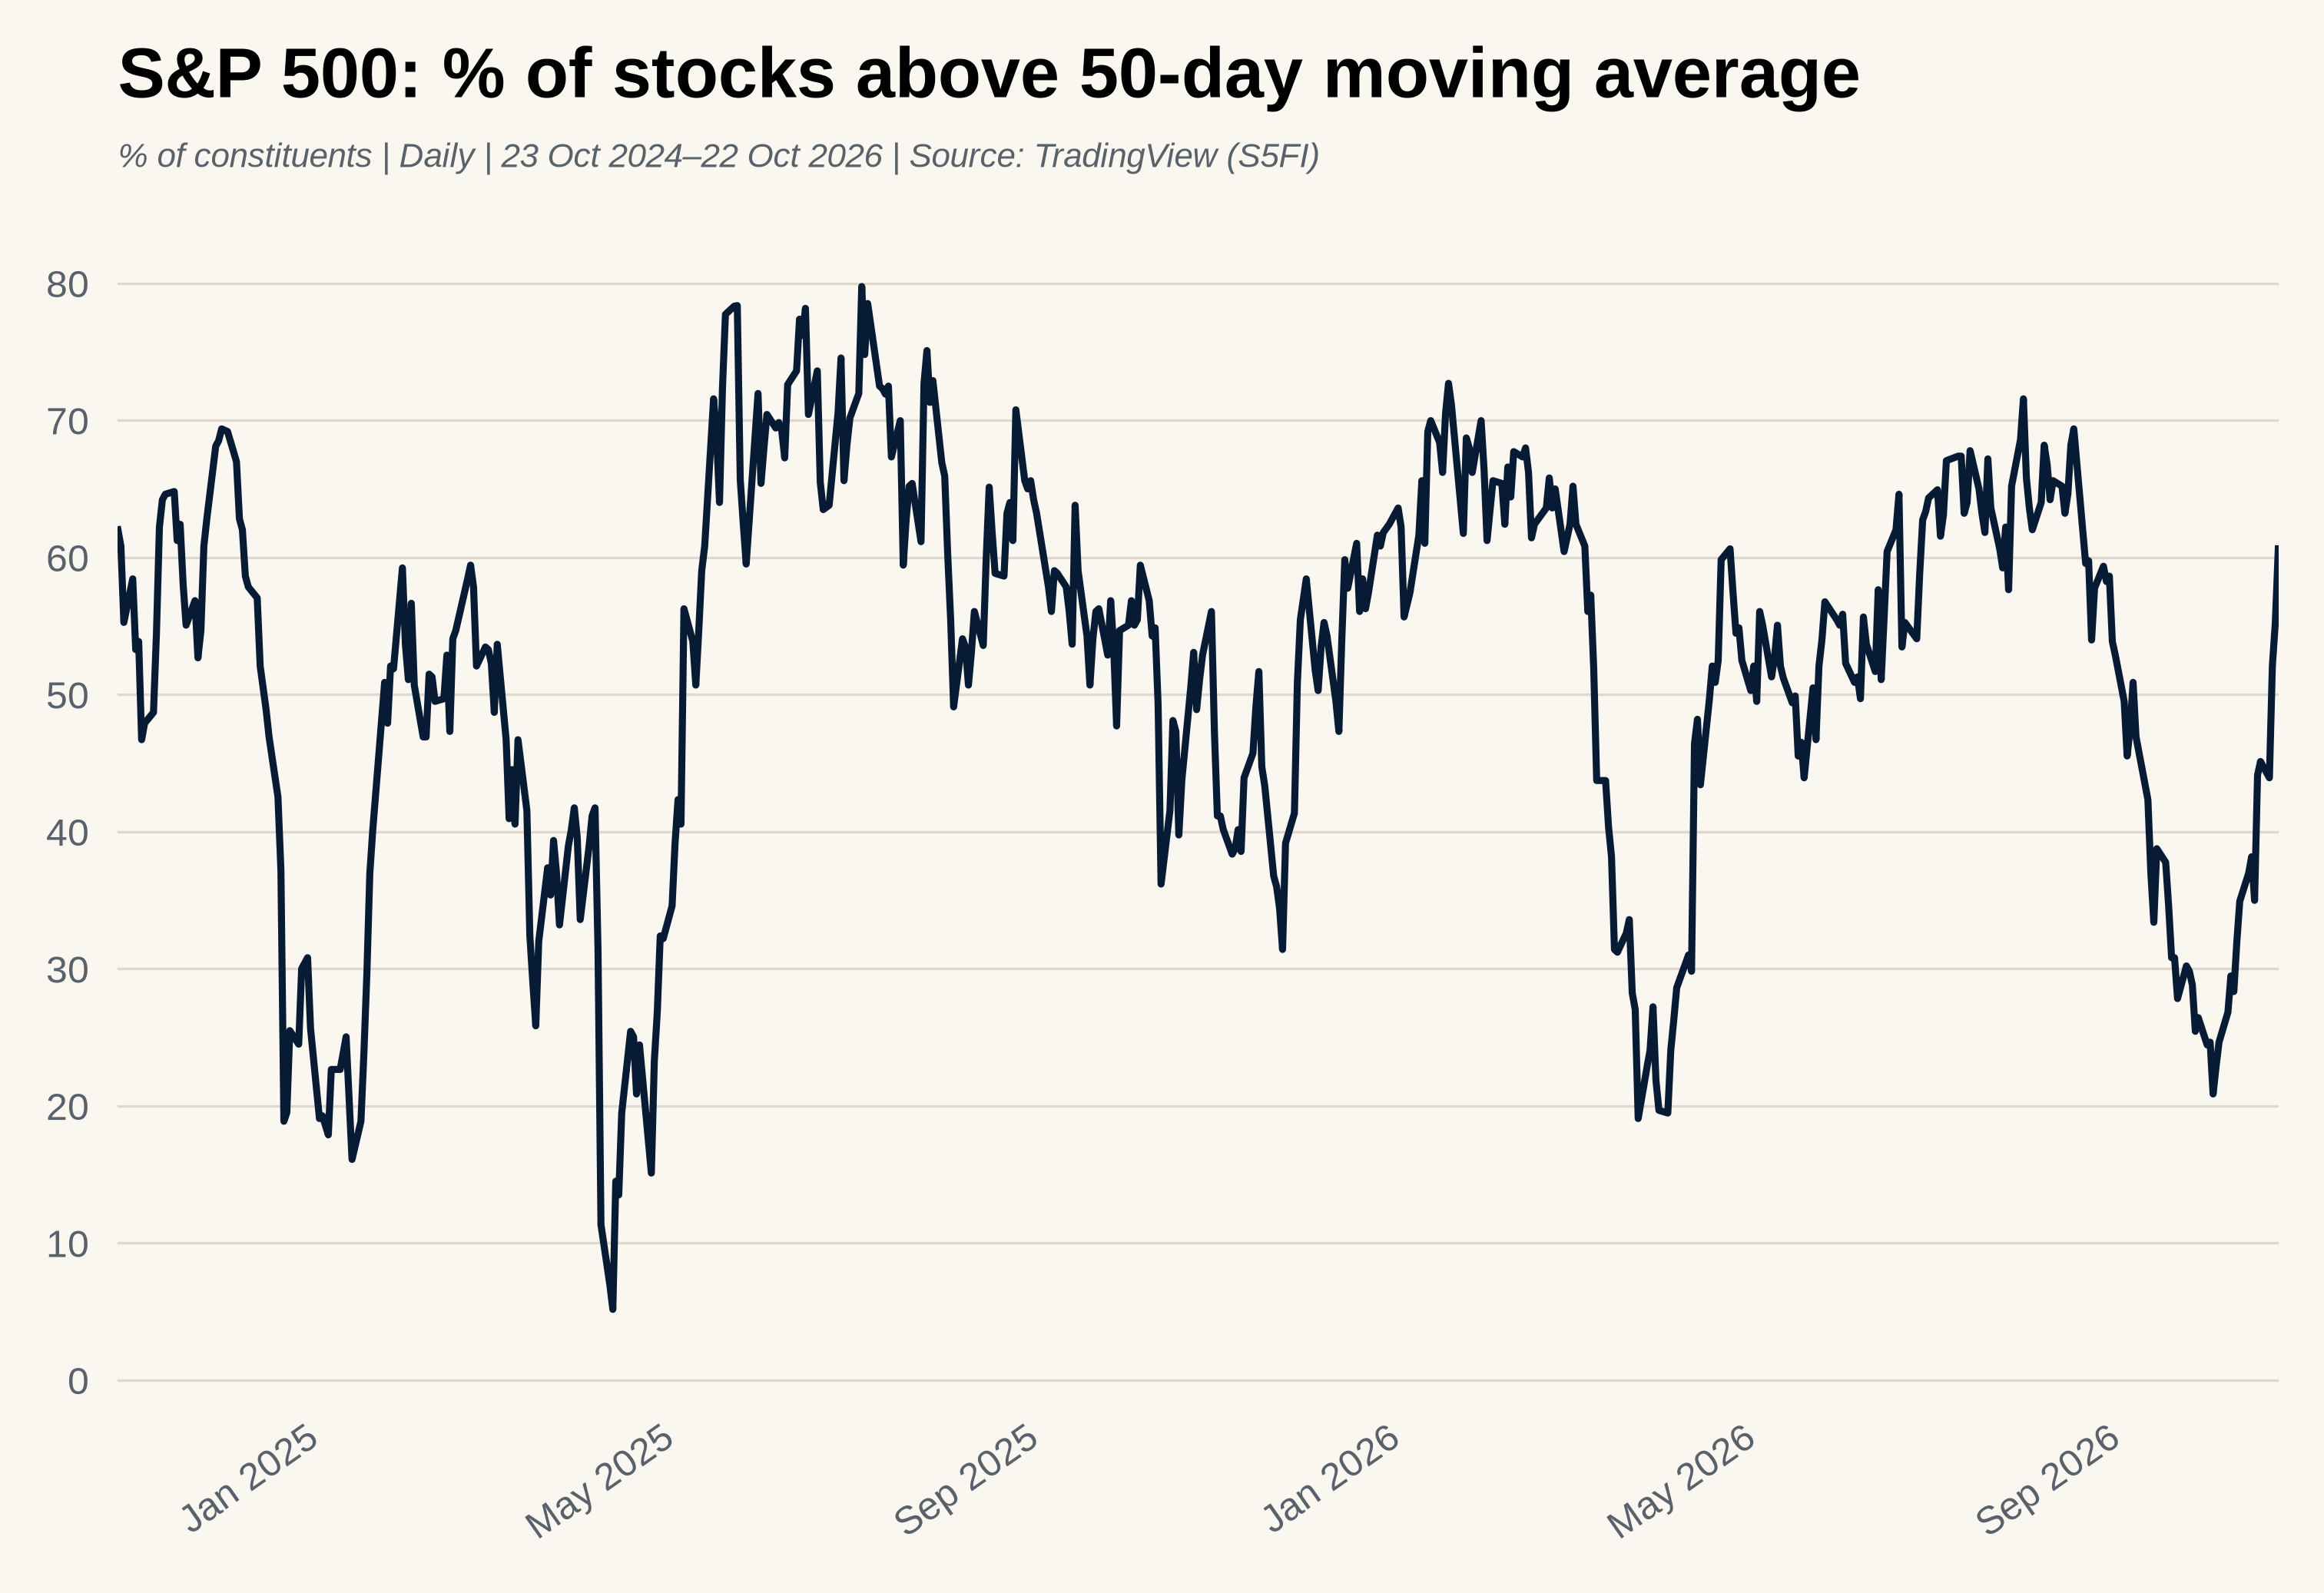
Actually, it’s quite the opposite. Look at breadth, for instance, which has markedly improved of late, with there now being well over half of stocks in the S&P trading above their 50-day moving averages.
Of course, the issue here is that with the SPX being so tech-heavy these days, you end up in a scenario where this significant sectoral churn results in the index going nowhere at all. Still, that probably speaks to the resilience of the market at large, given that the S&P is practically flat over the last 3 months, despite the 10-year yield having climbed 40-odd bp over that period.
So, short of being bearish, I’m quite the opposite. The US economy is going gangbusters, and earnings growth is ripping. Geopolitical jitters remain and may cause some near-term turbulence, while Fed tightening is another perennial worry, yet one that the economy looks able to withstand for now.
Does ‘buy the dip’ sound like a broken record? Yeah, it does.
But does it work? Yes. And, it’s still a strategy that I’d be advocating. The path of least resistance for equities is still one that leads higher.
Disclaimer
The information and opinions contained in this publication are provided for informational and educational purposes only and should not be construed as investment advice, a recommendation, or an offer to buy or sell any financial instrument.
All views expressed are solely those of the author and are subject to change without notice. While every effort is made to ensure the accuracy of the information presented, no representation or warranty is made as to its completeness or accuracy.
Readers should conduct their own research and, where appropriate, seek independent professional advice before making any investment or financial decisions. The author accepts no liability for any loss arising from reliance on the information contained in this publication.
Any references to specific securities, asset classes, markets, or investment strategies are provided solely for illustrative and analytical purposes and do not constitute investment recommendations.